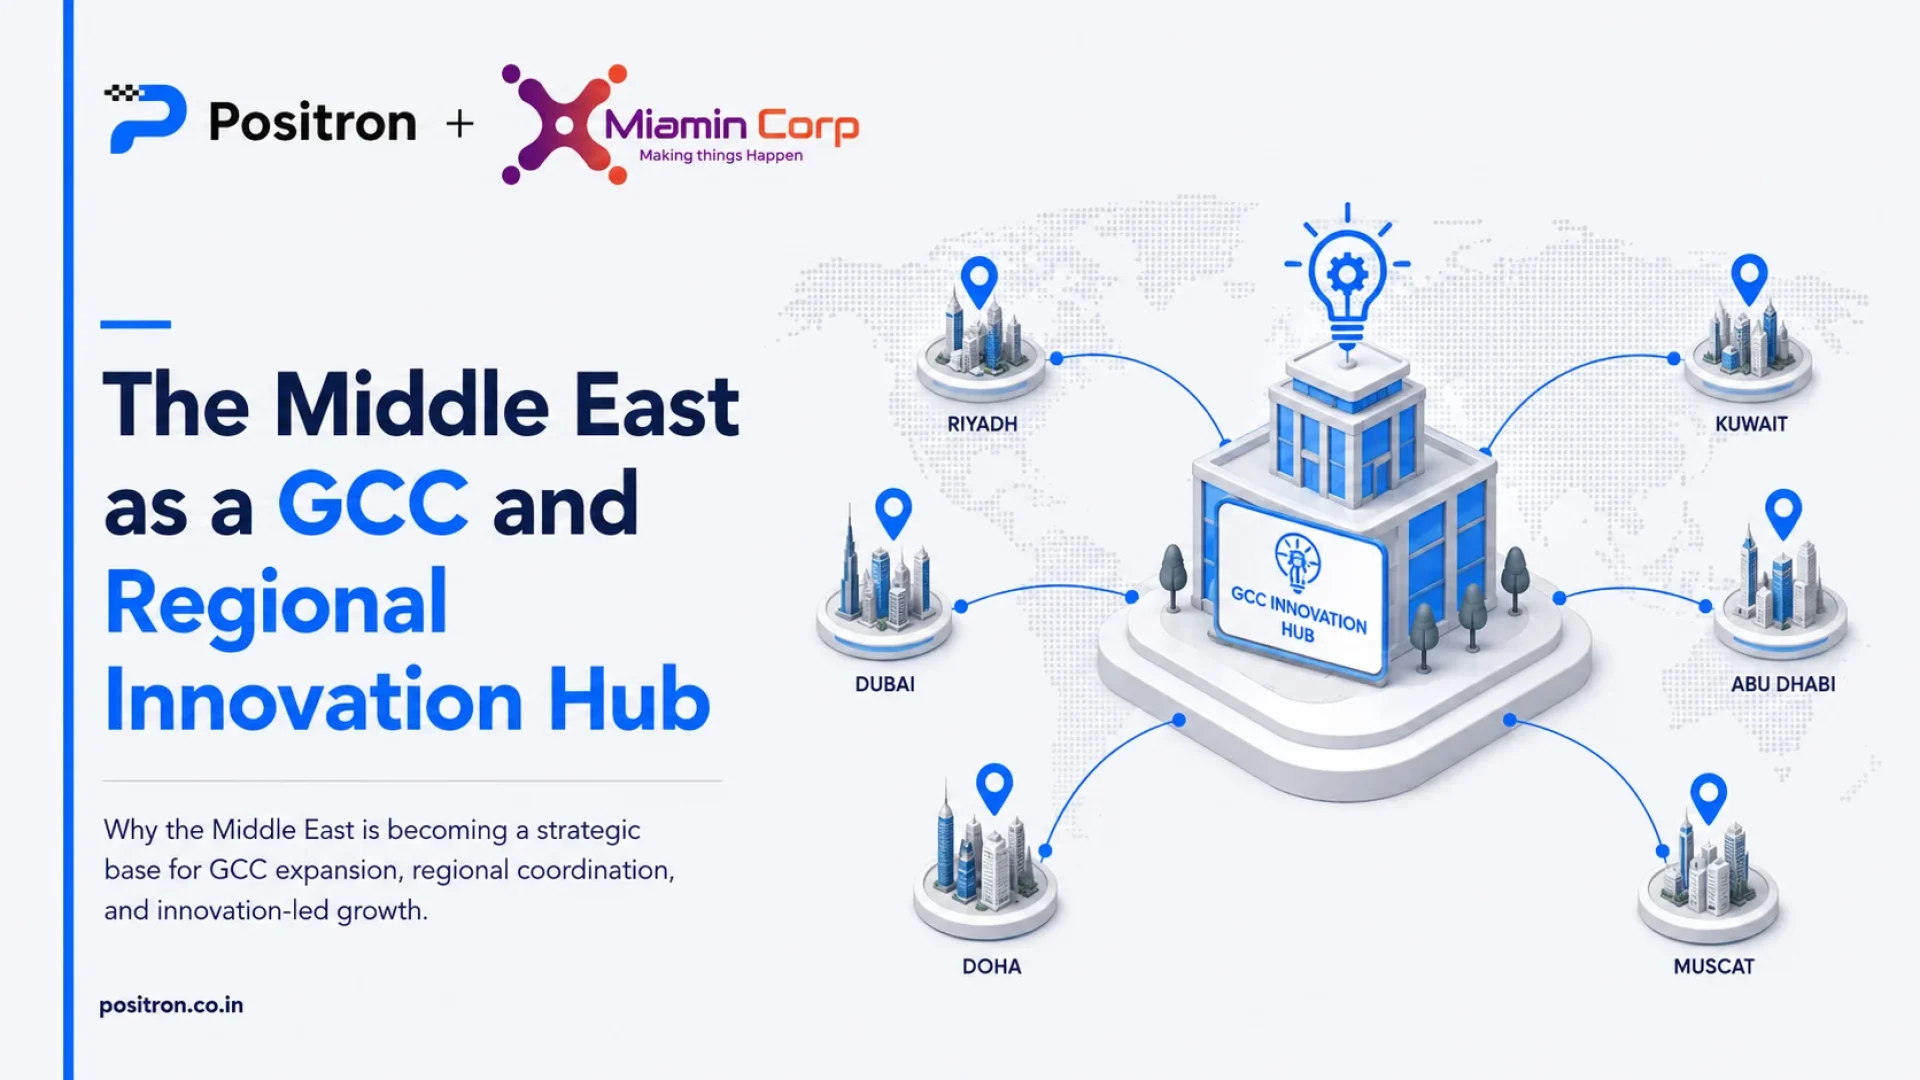
A well-designed hub can connect global products and operations with customers, regulators, infrastructure programmes and fast-moving digital agendas across the Gulf. That requires city-level evidence, country-specific diligence and leaders with genuine roadmap authority.
In our latest article, we explain how the region can complement engineering scale elsewhere with market intelligence, innovation access and faster local decisions.
In the Middle East, “GCC strategy” has two meanings: building a Global Capability Center and operating across the Gulf Cooperation Council. The most interesting opportunities sit where those two ideas meet.
The region should not be assessed as a substitute for a large offshore delivery market. Its differentiated value is regional proximity: access to customers, regulators, capital, infrastructure programmes and fast-moving digital agendas across the Gulf and the wider Middle East.
That can make a Middle Eastern centre useful as a market-facing capability and innovation node within a broader global portfolio.
Start with the regional mandate
A centre in the region can be designed to connect global platforms with local business realities. Potential mandates include regional product adaptation, Arabic-enabled customer experience, cybersecurity, financial services, energy and industrial technology, aviation and logistics, data and AI, or public-sector digital programmes.
These are not interchangeable. Each requires a different city ecosystem, regulatory assessment and leadership profile. A financial-services centre needs access to risk, compliance and fintech capability. An industrial centre may need engineering links and proximity to operating assets. A regional product hub needs customer research, commercial influence and decision rights—not simply developers in another office.
Public policy signals support this innovation-oriented view. The UAE’s Digital Economy Strategy, launched in 2022 and updated on the government portal in December 2024, aims to double the digital economy’s contribution to GDP over ten years. Saudi Arabia’s Digital Government Authority describes governance, shared platforms, human capability and modern technology as parts of its national transformation architecture. The World Bank’s December 2025 Gulf Economic Update highlighted advanced connectivity and growing investment in data centres, compute and AI, while also noting that economic diversification remains unfinished.
Those signals show direction. They do not guarantee that a particular enterprise can hire its required team at the necessary scale.
Treat the Middle East as several ecosystems
The Gulf is not one labour market or one regulatory environment. Entity rules, employment policies, data requirements, localisation expectations and sector regulation differ by country and can change. Talent depth also varies substantially by function and seniority.
Enterprises should therefore test a city and capability combination, not a regional brand. The diligence should cover:
- availability of the exact domain and leadership roles;
- nationalisation or localisation obligations and the associated workforce plan;
- data location, cross-border transfer and sector-specific controls;
- immigration and mobility for multinational teams;
- customer and regulator access;
- vendor, cloud and infrastructure dependencies;
- geopolitical and physical business-continuity scenarios; and
- fully loaded cost, including housing, mobility and senior talent premiums where relevant.
The aim is not to disqualify the region because it is complex. Complexity is precisely why a location can become strategically valuable: teams based there can convert regional context into faster and better enterprise decisions.
Give the centre a portfolio role, not a symbolic address
A small regional headquarters carrying a “GCC” label may create visibility without building capability. A stronger design links the node to global product, data and operating systems.
For example, a Middle East hub might own regional customer discovery, regulated partnerships and solution adaptation while an India centre provides engineering depth and another location supports Americas coverage. Product priorities, architecture, data access and service measures would be shared across the network.
This structure allows proximity and scale to complement each other. It also avoids forcing one location to perform work for which another ecosystem is better suited.
The leadership model is decisive. The regional centre needs executives who can influence both local stakeholders and global business owners. It needs the authority to shape roadmaps, not merely relay requests. It also needs governance that prevents local customisation from fragmenting the global platform.
The Middle East opportunity is therefore larger than establishing a delivery site. It is the chance to place decision-making closer to a region investing heavily in digital infrastructure, new industries and global connectivity.
The winning thesis is not “talent at a discount.” It is “regional intelligence connected to enterprise execution.”
Frequently Asked Questions
What are the biggest GCC trends in India?
Are GCCs in India still mainly technology centers?
Why is AI important for India GCCs?
What should companies watch before setting up a GCC in India?
Sources
- UAE Government, *Digital Economy Strategy* — launched April 2022; page updated 30 December 2024.
- Saudi Digital Government Authority, *Strategic Directions* — updated 17 April 2024.
- World Bank, *The Gulf’s Digital Transformation: A Powerful Engine for Economic Diversification* — 4 December 2025.
- UAE Government, *We the UAE 2031 Vision* — launched 22 November 2022.